How to file an insurance claim for storm damage to your roof
Filing an insurance claim for storm damage to your roof can be complex. This guide simplifies the process for Gainesville homeowners.
Filing an insurance claim for storm damage to your roof involves several steps, but knowing what to do can simplify the process. In Gainesville, Virginia, homeowners should understand their policy, assess the damage, and follow specific procedures to ensure a successful claim.
An insurance claim for storm damage is a request made to your insurance company to cover the costs of repairs or replacements needed due to damage caused by severe weather events. This guide will walk you through assessing storm damage, filing a claim, and avoiding common pitfalls.
What is an insurance claim for storm damage?
An insurance claim for storm damage is necessary when your roof sustains damage from events like hail, wind, or heavy rain. In Gainesville, these types of weather conditions can lead to significant damage that may require professional repair.
How to assess storm damage to your roof
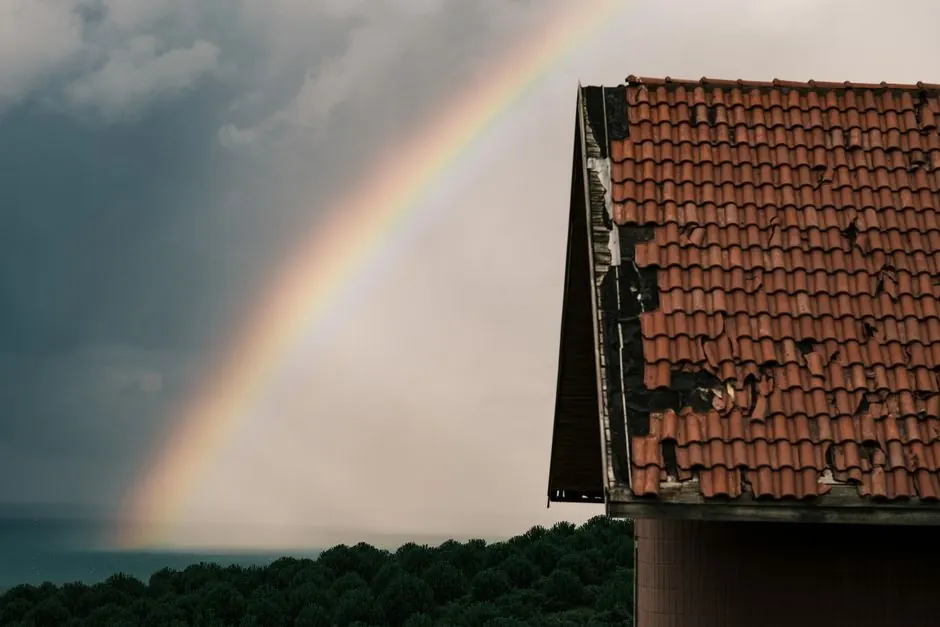
Assessing storm damage to your roof is a crucial first step in the claims process. Start by inspecting your roof for visible signs of damage, such as missing shingles, dents, or leaks. Use binoculars for a closer look, or consider hiring a professional for a thorough evaluation.
Here are some common signs of storm damage:
- Missing or damaged shingles
- Dents in metal roofing
- Leaks in the attic or ceiling
- Debris accumulation in gutters
Document all damage with photographs and written notes. This evidence will be essential when filing your claim. For homeowners in Gainesville, working with a local roofing inspection company in Gainesville can provide a detailed assessment and help you understand the extent of the damage.
Steps to file an insurance claim in Gainesville
Filing an insurance claim involves several key steps:
- Review Your Policy: Understand your coverage, including deductibles and limits for storm damage.
- Contact Your Insurance Company: Notify them of the damage as soon as possible.
- Submit Documentation: Provide photographs and a detailed description of the damage.
- Schedule an Inspection: Your insurance adjuster will need to assess the damage.
- Receive an Estimate: The adjuster will provide an estimate for the repairs.
- Complete Repairs: Once approved, you can begin repairs with a qualified contractor.
In Gainesville, it's advisable to contact a local storm damage repair company to assist with the repairs once your claim is approved. Their expertise can ensure that all work meets local standards.
Common mistakes when filing claims
Homeowners often make critical mistakes when filing insurance claims that can delay or even deny their claims. Here are some common pitfalls to avoid:
- Not documenting damage thoroughly.
- Waiting too long to file a claim.
- Failing to read the insurance policy carefully.
- Not following up with the insurance adjuster.
Being proactive and organized can significantly enhance your chances of a successful claim. If you are unsure about any part of the process, consider seeking insurance claims assistance in Gainesville to guide you through.
When to call a professional
Call a professional when you notice significant roof damage or if you experience leaks after a storm. It's also wise to consult a roofing expert if you feel overwhelmed by the claims process. Gainesville Roofing Experts can help assess the damage and guide you through filing your claim.
Frequently Asked Questions
1. How long do I have to file a claim after storm damage? Most insurance companies require you to file within a specific timeframe, typically between 30 to 90 days after the damage occurs.
2. Will my insurance cover all types of storm damage? Coverage varies by policy. Review your policy to understand what is covered and any exclusions.
3. What if my claim is denied? If your claim is denied, you can appeal the decision by providing additional documentation or seeking assistance from a claims expert.
4. How much will my deductible be? Deductibles vary by policy and can range from $500 to $2,500 or more, depending on your coverage.
5. Can I choose my contractor for repairs? Yes, you can choose your contractor, but ensure they are licensed and experienced in storm damage repairs.